

PPh 21 tax software that withholds TER in every payroll
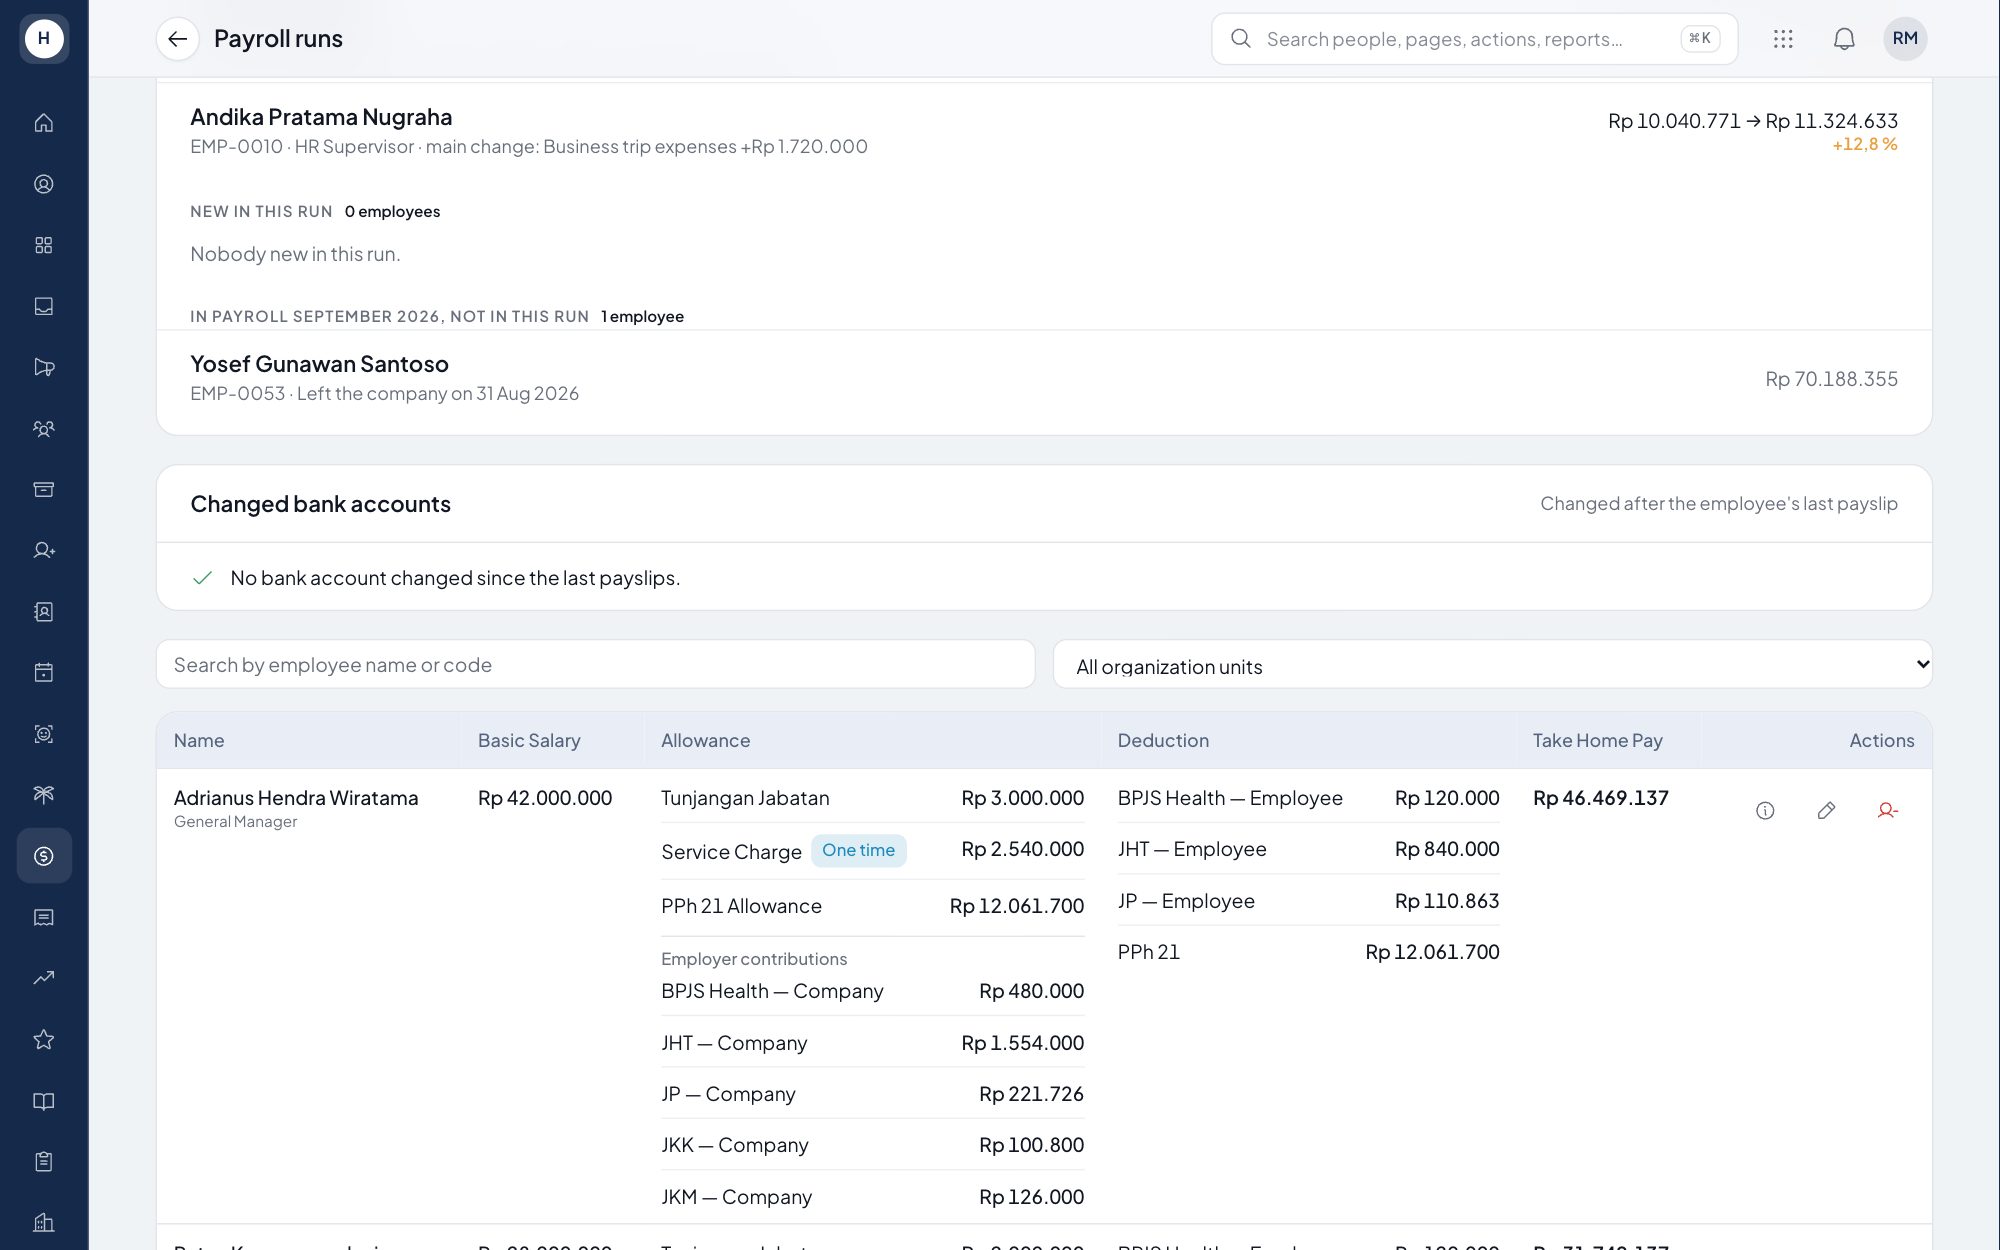
Stavis withholds PPh 21 every time payroll is calculated, using the TER rate for each employee's PTKP status. In the final tax period the year is recalculated at Article 17 rates, so the difference is settled on that payslip. Every deduction carries a calculation note you can show to an employee or an auditor.
What you can do
TER categories A, B and C
The employee's PTKP status sets the TER category under PP 58/2023. The tax base includes employer-paid BPJS Kesehatan, JKK and JKM premiums.
Article 17 true-up
In the final tax period, annual PPh 21 is recalculated at progressive Article 17 rates under PMK 168/2023, and any under- or over-withholding is settled on that payslip.
PPh 26 and daily TER
Foreign employees who are not tax residents are withheld under PPh 26. Daily workers are withheld under the daily TER.
Final PPh 21 on severance
Severance and separation pay are taxed with final PPh 21 at tiered rates and paid through payroll.
How it works
- 1
Complete tax data
Enter the NPWP or NIK and PTKP status. A PTKP change submitted by an employee is verified by HR before it is used.
- 2
Run payroll
PPh 21 is calculated with salary, allowances, overtime and BPJS. Tax rules are stored with effective dates, so older payslips stay correct.
- 3
Report to Coretax
From the locked payroll, build the PPh 21/26 recap per tax period and the e-Bupot files to upload to Coretax.
Frequently asked questions
How is PPh 21 TER calculated?
Add up the month's gross income, including employer-paid BPJS Kesehatan, JKK and JKM premiums, and multiply it by the TER rate for the PTKP category (A, B or C). You can try it in our free PPh 21 calculator at ozwals.com/pph-21-calculator.
What is the difference between TER categories A, B and C?
The category follows the PTKP status. TK/0, TK/1 and K/0 are category A; TK/2, TK/3, K/1 and K/2 are category B; K/3 is category C.
When is PPh 21 calculated at Article 17 rates?
In the final tax period, usually December or the month an employee leaves. The year's tax is calculated at Article 17 rates, PPh 21 already withheld is subtracted, and the difference is withheld or refunded on that payslip.
Are employer JHT and JP contributions subject to PPh 21?
No. Employer-paid JHT and JP are not part of gross income. Employer-paid BPJS Kesehatan, JKK and JKM premiums are.
See Stavis with your own company
Bring one department, one shift pattern and one month of payroll. We will walk through it with you.
